- Thailand’s SEC proposed separate 5 million baht daily limits for stablecoin deposits and withdrawals at each operator.
- Customers would have to use wallets or accounts they own, with transfers to third-party wallets blocked.
- The draft also adds Travel Rule compliance, blockchain analytics and new disclosure rules for exchanges.
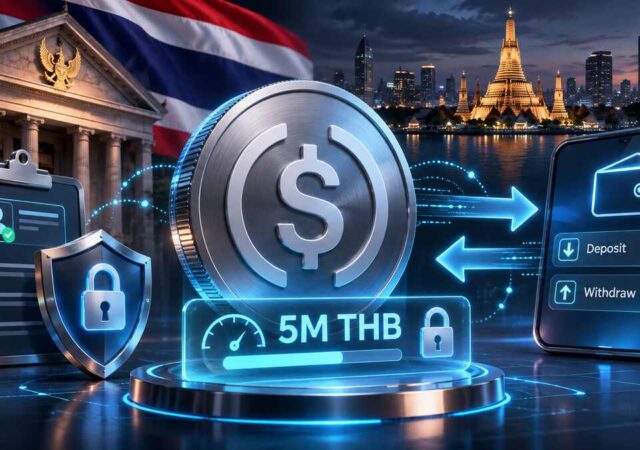
Thailand’s Securities and Exchange Commission has proposed a stablecoin cap that would limit daily deposits and withdrawals at regulated crypto operators. Under the draft, each customer could deposit up to 5 million baht and withdraw up to 5 million baht per day at each operator, with the two limits applied separately. The proposal also requires operators to verify that customers use wallets or accounts they own and would block transfers to and from third-party wallets. The SEC said the measures are intended to curb money laundering, cybercrime and efforts to get around cross-border money transfer rules. The draft follows a September consultation on stablecoin transfers and broader crypto oversight.
Stablecoin cap sets separate daily limits
The proposed stablecoin cap would apply to deposits and withdrawals as two distinct limits rather than one combined ceiling. Thailand’s SEC said each customer would be subject to a 5 million baht daily cap for stablecoin deposits and a separate 5 million baht daily cap for stablecoin withdrawals at each regulated operator.
That structure means the rule would work at the platform level, with the cap applied separately at each operator. The regulator said the purpose of the draft is to address money laundering, cybercrime and attempts to bypass cross-border transfer rules, placing the stablecoin cap within a wider compliance framework rather than treating it as a standalone restriction.
Wallet ownership checks and transfer restrictions
A central part of the stablecoin cap proposal is a ban on transfers to and from third-party wallets. Instead, regulated operators would need to verify that the wallet or account used for deposits and withdrawals belongs to the customer making the transaction.
The SEC’s draft links these wallet checks to stronger oversight of stablecoin movements. By requiring customer-owned wallets and accounts, the regulator is trying to reduce risks tied to hidden counterparties and unclear fund flows. In practice, the stablecoin cap would be paired with tighter identity and ownership verification for transfer activity.
Stablecoin cap adds compliance duties
The draft would also require crypto operators to comply with the Travel Rule. That would obligate service providers to collect and share information connected to transfers, adding a formal reporting layer to stablecoin transactions covered by the stablecoin cap.
In addition, operators would have to use blockchain analytics to identify wallets associated with suspicious activity. These tools would extend monitoring beyond basic transaction processing. Together, the Travel Rule and blockchain analytics show that the stablecoin cap is part of a broader plan for tighter supervision of how funds move through regulated crypto platforms.
Trading rules linked to the stablecoin cap
Thailand’s SEC included other market structure measures in the same draft. Crypto exchanges would be required to identify their market makers and specify which assets those market makers support with liquidity.
The regulator also said crypto brokers would be barred from using liquidity providers for stablecoin-baht pairs. Certain off-platform trades would face a 3 million baht minimum as well. These measures do not change the daily stablecoin cap itself, but they add trading and disclosure conditions that would shape how regulated firms handle stablecoin activity.
Conclusion
Thailand’s proposed stablecoin cap would combine transfer limits with tighter controls on wallet use, compliance and market activity. The SEC wants regulated operators to apply separate 5 million baht daily limits to stablecoin deposits and withdrawals, while also ensuring that customers use wallets or accounts they own. The draft adds Travel Rule obligations, blockchain analytics requirements, market maker disclosure and restrictions involving stablecoin-baht liquidity and certain off-platform trades. According to the regulator, the overall goal is to reduce money laundering, cybercrime and attempts to avoid cross-border transfer rules. The proposal builds on a September consultation that already signaled stricter oversight for crypto operators.
Disclaimer
The information provided in this article is for informational purposes only and should not be considered financial advice. The article does not offer sufficient information to make investment decisions, nor does it constitute an offer, recommendation, or solicitation to buy or sell any financial instrument. The content is opinion of the author and does not reflect any view or suggestion or any kind of advise from CryptoNewsBytes.com. The author declares he does not hold any of the above mentioned tokens or received any incentive from any company.
Featured image created by AI